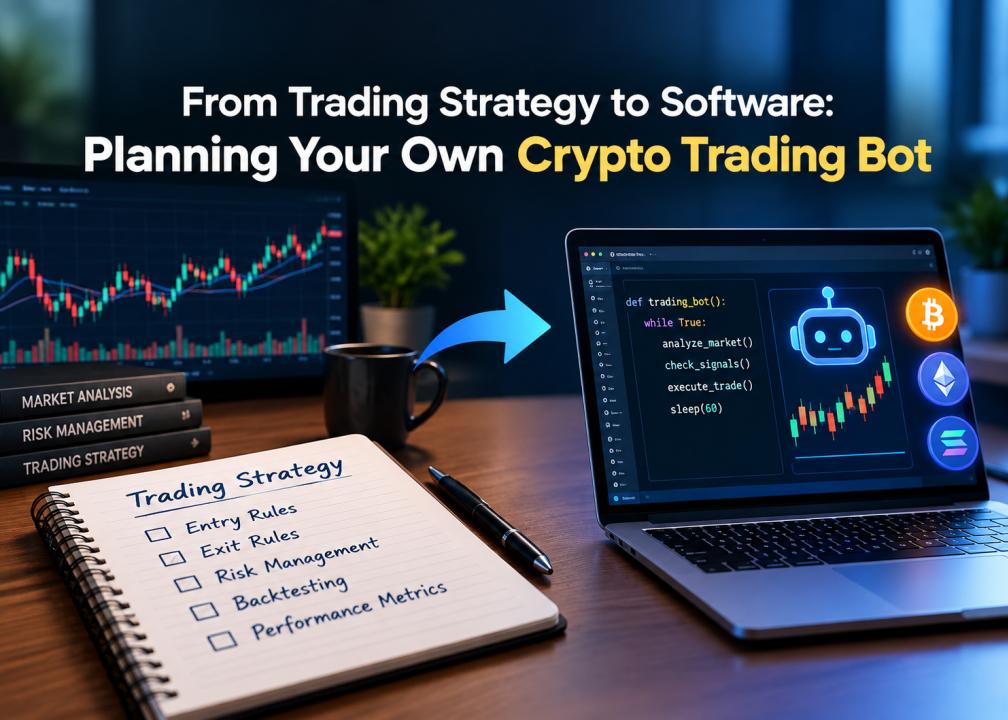
Cryptocurrency markets operate continuously, creating opportunities that can emerge and disappear within seconds. For traders and businesses, responding to these movements manually can become difficult as market data, liquidity conditions, and trading signals change throughout the day. A crypto trading bot addresses this challenge by converting a trading strategy into software that monitors market conditions, evaluates predefined rules, and executes orders automatically.
However, building a reliable trading bot involves considerably more than connecting an algorithm to an exchange. The development process requires a clear trading hypothesis, suitable system architecture, robust risk controls, secure API integration, and a structured testing methodology. Understanding these elements before development begins helps turn a trading idea into a practical software product that can be evaluated, maintained, and improved over time.
Turning a Trading Strategy into Software Requirements
Every trading bot begins with a strategy that can be expressed as measurable conditions. A trader might identify opportunities using moving-average crossovers, relative strength index (RSI), order-book imbalances, funding-rate differences, or statistical relationships between digital assets. The development challenge is to translate these observations into precise instructions that software can execute consistently.
A strategy should define its entry conditions, exit criteria, position sizing, holding period, and maximum acceptable exposure. It must also explain what the bot should do when signals conflict, market data becomes unavailable, or an order remains partially filled. These scenarios are important because real markets rarely behave as cleanly as historical charts suggest.
Before development, establish the following requirements:
- Trading objectives: Determine whether the system targets trend following, market making, arbitrage, portfolio rebalancing, or another strategy.
- Market selection: Specify supported trading pairs, exchanges, order types, and liquidity requirements.
- Execution rules: Establish order placement, cancellation, retry logic, and handling of partial fills.
- Risk parameters: Set position limits, drawdown thresholds, stop-loss conditions, and exposure restrictions.
- Performance measurements: Define metrics such as net returns, maximum drawdown, Sharpe ratio, turnover, and execution slippage.
These requirements provide a practical foundation for development. They also help distinguish between a strategy that appears attractive in theory and one that remains viable after trading fees, latency, and market impact are considered.
Choosing the Right Architecture and Exchange Connectivity
Once the trading logic is defined, the next step is designing the software architecture. A trading bot typically includes market-data ingestion, signal generation, portfolio and risk management, order execution, persistent storage, monitoring, and a user interface. Each component should have a clear responsibility so that changes to one module do not destabilize the entire system.
Market-data ingestion collects prices, trades, order-book snapshots, and other relevant information through exchange APIs or WebSocket streams. The strategy engine processes these inputs and generates trading signals. A separate execution engine validates those signals against risk limits before submitting orders.
Separating signal generation from execution is particularly valuable. A strategy may identify a valid opportunity, but the execution layer should reject the trade if available balance is insufficient, the market has become too volatile, or the expected return no longer covers transaction costs.
Technology choices depend on the intended trading frequency, deployment environment, and expected workload. Python is commonly used for research, data analysis, and machine-learning experimentation, while languages such as Go, Java, or Rust may suit particular performance-sensitive services. The appropriate choice depends on measured requirements rather than assumptions that one language guarantees better trading results.
Exchange connectivity requires equal attention. API rate limits, authentication mechanisms, supported order types, market-data reliability, and exchange-specific trading rules can affect execution quality. Systems operating across multiple exchanges must also normalize differences in symbol formats, precision requirements, minimum order sizes, and response codes.
Businesses exploring arbitrage strategies may evaluate a Crypto Arbitrage trading bot development company when assessing the technical expertise required for multi-exchange connectivity, automated execution, and transaction-cost analysis. Arbitrage opportunities must be evaluated against actual execution conditions rather than price differences alone.
A well-designed architecture should also account for asynchronous processing, timestamp synchronization, persistent order states, and recovery after service interruptions. If an application restarts while an order is still active, it must reconcile its internal records with the exchange before resuming trading. Otherwise, duplicate orders or incorrect position calculations can create unintended exposure.
Building Execution, Risk Management, and Security Controls
A trading strategy determines when to seek an opportunity; execution logic determines whether that opportunity can be acted upon efficiently. This distinction matters because a profitable signal can become unprofitable when orders are delayed, spreads widen, or available liquidity disappears.
Market orders prioritize execution but may experience substantial slippage in thin order books. Limit orders offer price control but introduce the possibility of non-execution or partial fills. The bot must select an order type appropriate to the strategy, liquidity conditions, and acceptable execution risk.
Transaction-cost modelling should include maker and taker fees, bid-ask spreads, funding payments where applicable, network fees for on-chain operations, and expected slippage. In multi-exchange strategies, withdrawal delays, transfer costs, and balance availability can further affect the economics of a trade. An apparent arbitrage opportunity is not necessarily profitable once these factors are included.
Risk management must operate independently of the strategy engine. A model should never be allowed to bypass essential portfolio constraints simply because its confidence score is high. Practical controls include maximum order values, asset-level exposure limits, daily loss thresholds, and circuit breakers that pause trading when market data or execution behaviour becomes unreliable.
Security is equally important because exchange API credentials can authorize sensitive operations. A defensible implementation should use encrypted secrets management, least-privilege API permissions, restricted withdrawal permissions, access logging, and controlled deployment environments. Where supported, exchange API keys should be restricted to approved IP addresses.
The system should also maintain an auditable record of signals, orders, fills, rejected trades, and risk interventions. These records make it easier to investigate discrepancies between expected and actual performance. For AI-enabled bots, machine-learning models should undergo validation to identify overfitting and unstable predictions. Their outputs should pass through deterministic risk checks before reaching the execution engine.
Testing, Deployment, and Continuous Performance Evaluation
Testing is where a trading hypothesis begins to face practical evidence. Historical backtesting provides an initial assessment of whether a strategy would have performed under recorded market conditions. However, a backtest is only as reliable as its data, assumptions, and execution model.
A robust testing process separates development data from validation and out-of-sample periods. This reduces the risk of selecting parameters that fit historical noise rather than a repeatable market pattern. For more complex strategies, walk-forward analysis can help evaluate how performance changes when models are periodically recalibrated using newer data.
The simulation should account for trading fees, realistic order fills, slippage, funding costs, and market liquidity. Strategies that depend on very short-lived price differences need particular scrutiny because historical candles cannot fully represent order-book dynamics or execution latency.
Before live deployment, the bot should operate in a paper-trading environment or exchange sandbox where available. This allows developers to examine signal quality, order-state transitions, API failures, and recovery behaviour without immediately committing capital. Paper trading is useful, although it cannot reproduce every condition of live execution.
During deployment, the development team should monitor several operational and financial indicators:
- Execution performance: Track order rejection rates, fill ratios, slippage, and execution latency.
- System reliability: Monitor API availability, stale market data, processing delays, and unexpected service interruptions.
- Portfolio exposure: Review open positions, asset concentration, margin utilization, and drawdown against predefined limits.
- Strategy effectiveness: Compare actual results with backtested expectations, accounting for transaction costs and changing market conditions.
- Recovery behaviour: Verify that the bot can reconcile balances and open orders after restarts or exchange connectivity failures.
Performance evaluation must extend beyond headline returns. Maximum drawdown measures the largest decline from a portfolio peak, while the Sharpe ratio relates excess returns to return volatility. Win rate, profit factor, turnover, and average execution cost provide additional context. No single metric establishes that a strategy will remain profitable in the future.
After launch, changes should follow a controlled release process. Strategy updates need regression testing, configuration changes require review, and model retraining should be validated before deployment. A trading bot is an evolving software system, not a one-time coding project.
Why Choose Shamla Tech for AI Crypto Trading Bot Development?
Choosing a development partner requires evaluating its ability to understand trading requirements and translate them into dependable software. The team should be able to address exchange integration, data pipelines, algorithm design, execution workflows, security, and production monitoring as interconnected engineering challenges.
Shamla Tech offers crypto trading bot development services covering custom trading software, AI and machine-learning integration, automated execution, and multi-exchange functionality. These capabilities are relevant to businesses that want to develop a bot around a specific trading strategy instead of relying entirely on a generic, preconfigured product.
A project should begin with technical discovery, including strategy requirements, exchange selection, expected trading frequency, risk limits, and infrastructure needs. From there, the development team can establish an architecture, implement the required modules, and validate system behaviour through simulation and controlled testing.
For businesses exploring AI-driven automation, machine-learning components can support market analysis, pattern recognition, or anomaly detection where the use case justifies them. Their effectiveness should be measured against appropriate baselines, with risk controls maintained independently of predictive models.
Before engaging a development partner, businesses should confirm the project scope, security practices, deliverables, testing criteria, maintenance arrangements, and ownership of the developed software. These details help establish clear expectations and make the final solution easier to evaluate.
Conclusion
Planning a crypto trading bot starts with a well-defined strategy and progresses through architecture design, exchange integration, execution engineering, risk management, and systematic testing. Each stage influences the reliability of the finished product. A sophisticated algorithm cannot compensate for inaccurate market data, poor order handling, inadequate security, or unrealistic performance assumptions.
The most effective approach is to begin with a clearly scoped use case, validate its underlying assumptions, and develop the system incrementally. By prioritizing measurable performance, transparent risk controls, and operational resilience, businesses can build trading software that is easier to maintain and assess under changing market conditions. Automation can improve consistency and execution speed, but it cannot eliminate market risk or guarantee profits.