Market Overview
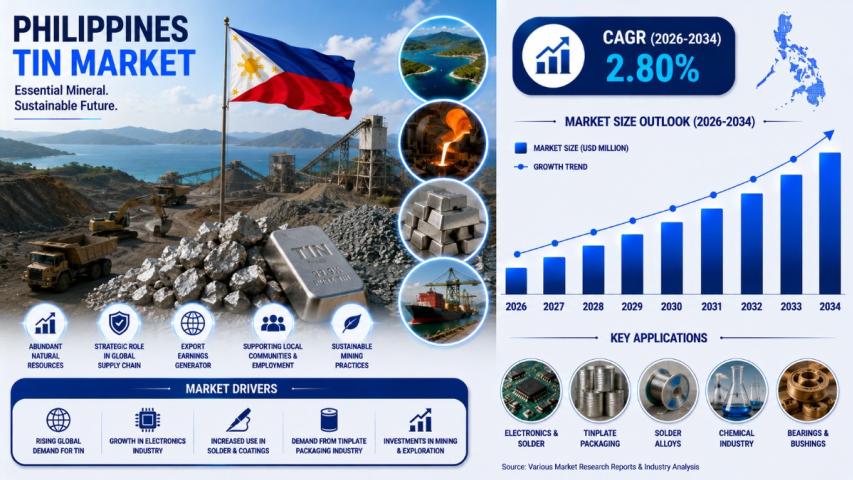
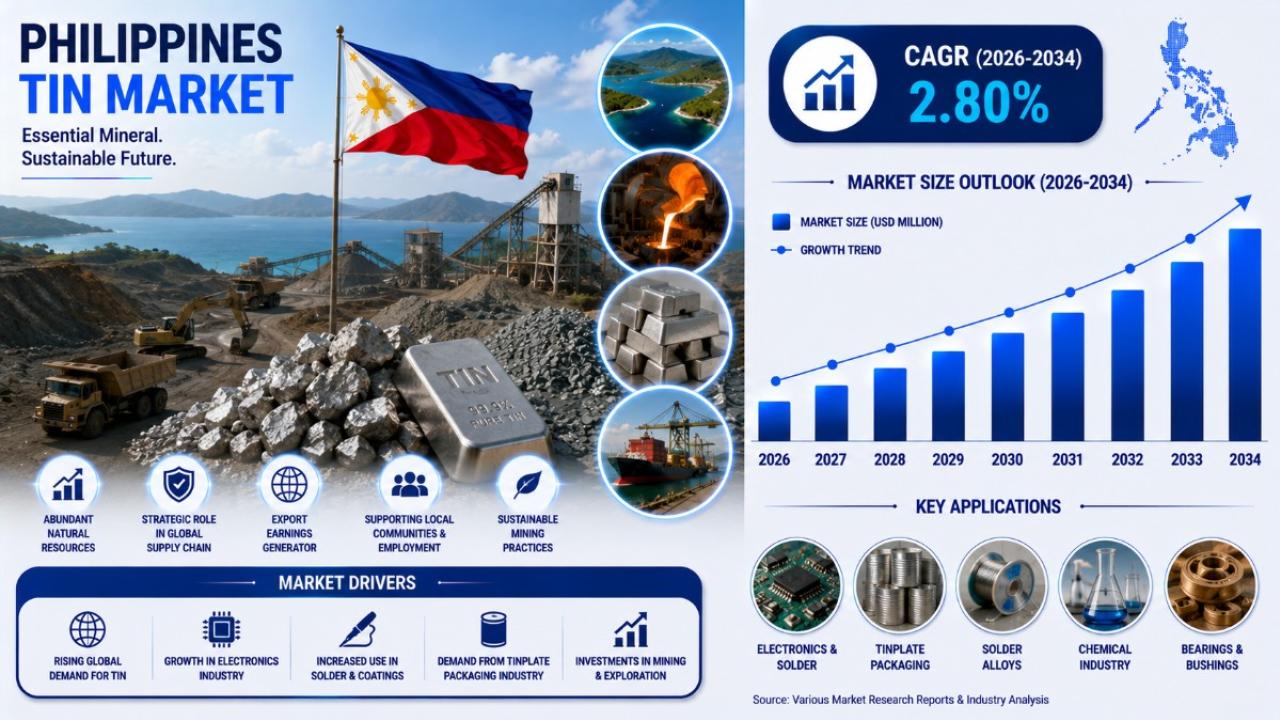
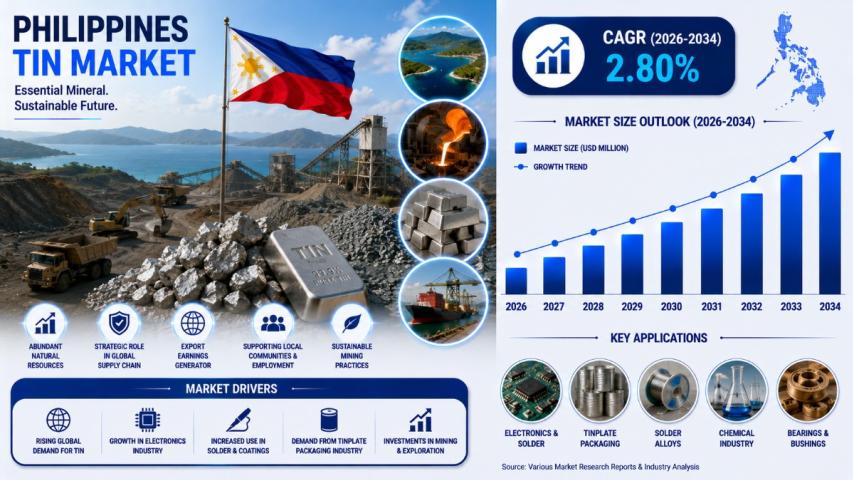
The Philippines tin market size reached 1.91 Kilo Tonnes
in 2025 and is projected to reach 2.46 Kilo Tonnes by 2034, growing
at a compound annual growth rate of 2.80% from 2026-2034. The market is
driven by expanding electronics manufacturing activities, increasing adoption
of tin-based soldering materials in consumer electronics and automotive
applications, and growing demand from the food packaging sector. Rising industrial
development and infrastructure investments, coupled with technological
advancements in tin processing and alloy production, continue to strengthen
domestic consumption patterns. Additionally, supportive government policies
promoting manufacturing growth and export competitiveness further reinforce
market expansion, contributing to the Philippines tin market share.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/philippines-tin-market/requestsample
Philippines Tin Market Summary
- The
Philippines tin market encompasses a range of products, including metal,
alloy, and compounds, serving soldering, tin plating, chemicals, and other
applications across automotive, electronics, packaging (food and
beverages), glass, and other end-use industries.
- These
products are valued for their role in providing reliable electrical
connections, corrosion resistance, food safety properties, and material
performance across various industrial and consumer applications.
- The
ecosystem includes tin processors, refiners, international trading
entities, industrial suppliers, distributors, manufacturers, and
end-users.
- Major
segments identified in the market include product type (metal, alloy,
compounds), application (soldering, tin plating, chemicals, others),
end-use industry (automotive, electronics, packaging, glass, others), and
region (Luzon, Visayas, Mindanao).
- The
market is benefiting from expanding electronics manufacturing and export
activities, growing automotive sector and vehicle electronics integration,
rising demand from food and beverage packaging applications, and strategic
investments in domestic processing capabilities.
- In
2025, the Philippine government established a Semiconductor and
Electronics Industry Advisory Council to accelerate electronics
manufacturing and strengthen global competitiveness, directly supporting
downstream demand for tin-based solder materials.
PORTER'S FIVE FORCES ANALYSIS
- Competitive
Rivalry: Moderate, with established regional processors competing
alongside international trading entities across various industrial
segments and application categories. Business implication: Companies
must differentiate through product quality, supply chain reliability, and
technical expertise.
- Supplier
Power (Raw Materials): High. Suppliers of tin ore, concentrates, and
refined tin materials have significant leverage due to limited domestic
mining and refining capacity, creating dependence on imported materials. Business
implication: Processors should diversify supply sources and invest in
domestic processing capabilities.
- Buyer
Power (Consumers): Moderate. Industrial buyers have choice across
suppliers, product specifications, and price points, with growing
awareness of quality standards and supply chain reliability. Business
implication: Suppliers must focus on quality, reliability, and
technical support to build loyalty.
- Threat
of Substitutes: Moderate. Alternative materials (aluminum packaging,
polymer-based solutions, conductive adhesives) compete, but the
performance characteristics and established applications of tin support
its position. Business implication: The industry should emphasize
performance advantages, quality, and cost-effectiveness.
- Threat of New Entrants: Moderate. Higher barriers for established processors (scale, distribution, certifications, supply chains), but lower barriers for niche and specialized entrants. Business implication: Established players should build defensible positions through innovation and brand equity.
MARKET GROWTH DRIVERS
Expanding Electronics Manufacturing and Export Activities
The Philippines maintains a robust electronics manufacturing
sector representing a significant contributor to national export revenues and
industrial employment. Major international electronics brands utilize
Philippine manufacturing facilities for producing consumer devices, computing
equipment, and electronic components destined for global markets. As per
sources, in November 2025, Samsung Electro-Mechanics Philippines announced a
PhP50.7 Billion investment to expand its high-technology manufacturing facility
in Laguna, reflecting stronger electronics production and downstream demand for
tin-based solder materials. Moreover, this manufacturing concentration
generates substantial demand for tin-based soldering materials essential in
circuit board assembly processes.
Growing Automotive Sector and Vehicle Electronics Integration
The Philippine automotive industry demonstrates steady
expansion, driven by increasing domestic vehicle ownership and manufacturing
investment. Modern automobiles incorporate extensive electronic components
requiring tin-based solder connections for engine management systems,
infotainment units, and safety systems. The proliferation of advanced
driver-assistance features and connected vehicle technologies amplifies tin
consumption per vehicle unit. Domestic automotive assembly operations generate
incremental demand for high-quality tin materials meeting automotive-grade
specifications. As per sources, in December 2024, Toyota Motor Philippines
invested ₱5.5 Billion to revive Tamaraw production, strengthening local
automotive parts manufacturing and enhancing the national automotive value chain.
Rising Demand from Food and Beverage Packaging Applications
The Philippine food and beverage industry demonstrates sustained growth, driven by expanding population and rising disposable incomes. Tin-plated steel containers offer superior corrosion resistance, food safety properties, and extended shelf-life characteristics valued by manufacturers and consumers alike. Growing urbanization and changing life>
PHILIPPINES TIN MARKET SEGMENTATION
Product Type Insights:
- Metal
- Alloy
- Compounds
Application Insights:
- Soldering
- Tin
Plating
- Chemicals
- Others
End-Use Industry Insights:
- Automotive
- Electronics
- Packaging
(Food and Beverages)
- Glass
- Others
Regional Insights:
- Luzon
- Visayas
- Mindanao
COMPETITIVE LANDSCAPE
The Philippines tin market features a moderately fragmented
competitive structure characterized by the participation of established
regional processors, international trading entities, and specialized industrial
suppliers serving diverse end-use segments. Market participants differentiate
through product quality specifications, supply reliability, technical support
capabilities, and pricing competitiveness across various application
categories. Distribution networks and customer relationships developed over
extended operating periods provide competitive advantages for established
market participants. The competitive environment encourages continuous
improvement in processing efficiency, quality control systems, and customer
service responsiveness. Strategic partnerships between domestic processors and
international suppliers enhance material availability and market reach.
Key players mentioned in the report context include:
- The
market research report has also provided a comprehensive analysis of the
competitive landscape. Competitive analysis such as market structure, key
player positioning, top winning strategies, competitive dashboard, and
company evaluation quadrant has been covered in the report. Also, detailed
profiles of all major companies have been provided.
REGIONAL ANALYSIS
- Luzon:
Leads with a 48% share in 2025, driven by concentrated industrial
activity, superior infrastructure development, proximity to major
commercial centers, Metro Manila and surrounding industrial zones hosting
numerous electronics manufacturing facilities, and special economic zones
attracting foreign investment.
- Visayas:
A significant market driven by growing industrial development, increasing
electronics manufacturing activities, expanding food processing
operations, and improving infrastructure connectivity supporting tin
consumption across diverse applications.
- Mindanao:
A growing market with expansion driven by agricultural processing
activities, growing food packaging demand, increasing industrial
investment, and improving logistics infrastructure supporting tin material
distribution.
RECENT INDUSTRY DEVELOPMENTS
September 2026: Global tin supply-chain risks remained a key issue for electronics manufacturers as Myanmar’s tin production continued to influence regional availability. A recent International Crisis Group report noted that tin prices had reached above US$53,000 per tonne in January 2026, driven partly by demand associated with AI data centers. Tin is widely used in solder for electronics, making developments in major Asian supply sources relevant to Philippine manufacturers.
August 2026: Tin remained closely linked to the expansion of electronics and semiconductor manufacturing in Southeast Asia. The Philippines' electronics industry continues to be a major source of domestic tin demand, particularly for soldering applications. IMARC estimates that electronics accounted for 35% of Philippine tin consumption in 2025, while soldering represented 40% of applications.
July 2026: The Philippines continued strengthening its advanced manufacturing ecosystem, supporting downstream demand for tin-based materials. IMARC reports that the country opened its 7th Advanced Manufacturing Center in Laguna in September 2025, supporting additive manufacturing, materials development, and advanced industrial components. Such manufacturing capabilities complement the electronics and automotive industries that consume tin-based solder and alloys.
Key Aspects Required for the Philippines Tin Market
- Market
Performance: 1.91 Kilo Tonnes in 2025, with a projected trajectory to
2.46 Kilo Tonnes by 2034.
- Market
Outlook: A 2.80% CAGR through 2034 indicates steady growth across
product types, applications, end-use industries, and regions, driven by
electronics manufacturing, automotive expansion, and food packaging
demand.
- Growth
Drivers: Expanding electronics manufacturing and export activities;
growing automotive sector and vehicle electronics integration; rising
demand from food and beverage packaging applications; strategic
investments in domestic processing capabilities; and integration of
advanced tin alloy technologies.
- Competitive
Landscape: A moderately fragmented market with established regional
processors, international trading entities, and specialized industrial
suppliers. Differentiation occurs through product quality specifications,
supply chain reliability, and technical expertise.
- Value
Chain Analysis: From tin ore sourcing and refining through processing,
alloy production, and distribution to end-use in electronics, automotive,
packaging, and other industrial applications, with technology and
regulatory trends shaping market dynamics.
- Industry
Trends: Transition toward lead-free soldering solutions; integration
of advanced tin alloy technologies; expansion of domestic tin processing
capabilities; and growing adoption of tin-based materials in automotive
electronics.
- Strategic
Recommendations: Invest in domestic tin processing and refining
capabilities; expand lead-free soldering and high-purity tin production;
develop advanced alloy technologies for automotive and electronics
applications; leverage government policies and import duty reductions; and
focus on supply chain resilience and quality control systems.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=42137&flag=C
Report Format, Delivery, and Customization Details
- Report
Format Mode: PDF and Excel (Editable version in PPT/Word format
available on special request)
- Report
Delivery Mode: Online Delivery, Physical Delivery
- Report
Delivery Time: report delivered over email within 24 to 48 hours. If
requested by the client, a physical copy will be delivered within three to
ten days.
- Report
Confirmation Mode: Yes, via email
- Report
Customization Mode: Yes, via Email / Call
- Report
Table of Content: Yes
- Report
List of Figures: Yes
- Report
Methodology Mode: Yes
- Request
For Sample Report: Yes
About Us
IMARC Group is a global management consulting firm that
helps the world's most ambitious changemakers to create a lasting impact. The
company provides a comprehensive suite of market entry and expansion services.
IMARC offerings include thorough market assessment, feasibility studies,
company incorporation assistance, factory setup support, regulatory approvals
and licensing navigation, branding, marketing and sales strategies, competitive
landscape and benchmarking analyses, pricing and cost research, and procurement
research.
Contact Us
IMARC Group
134 N 4th St., Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302