Next-Generation Lithium-ion Battery Market size and
growth
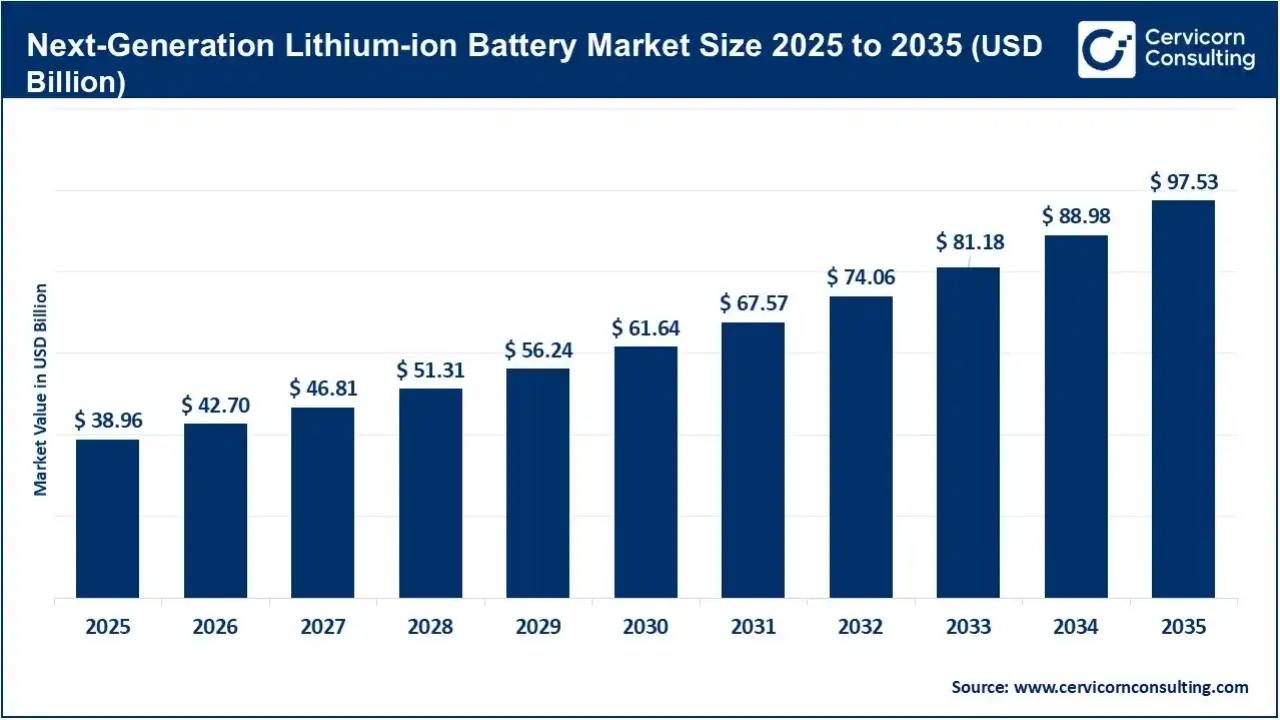
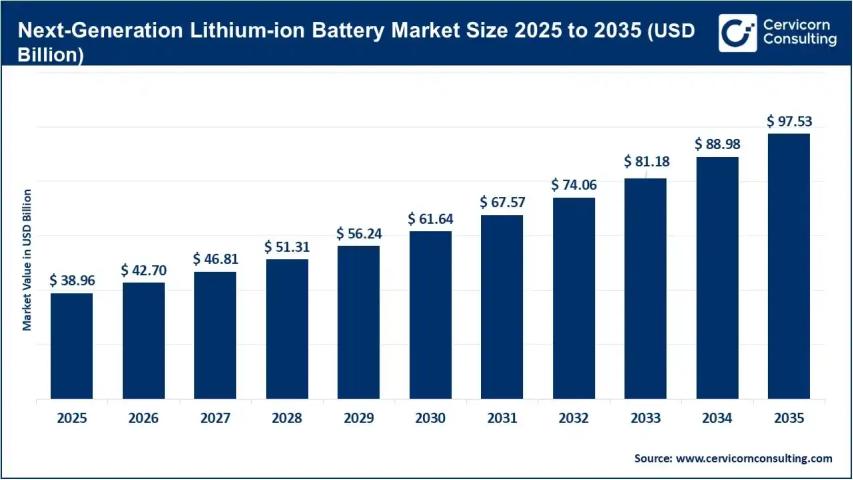
The global next-generation lithium-ion battery market
was valued at USD 38.96 billion in 2025 and is projected to exceed USD
97.53 billion by 2035, expanding at a 9.6% CAGR from 2026 to 2035.
Rising demand for higher energy density, faster charging, longer cycle life,
and improved battery safety is accelerating market growth.
EV electrification drives battery innovation
Global electric-car sales exceeded 17 million units in
2024, representing more than 20% of new-car sales worldwide. Global
EV battery deployment reached approximately 1.2 TWh in 2025, increasing
nearly 30% year over year. These trends are encouraging manufacturers to
develop silicon-based anodes, high-nickel cathodes, advanced electrolytes, and
improved cell architectures.
Silicon anodes and fast charging gain momentum
Silicon-based technologies are gaining attention because
silicon has a theoretical specific capacity of approximately 3,579 mAh/g,
substantially higher than conventional graphite. Average EV battery-pack energy
density has increased by around 60% over the past decade, while battery
prices have fallen by roughly 75%, strengthening the commercial
potential of advanced battery technologies.
Get a Free Sample: https://www.cervicornconsulting.com/sample/3023
Asia Pacific leads the market
Asia Pacific held a 52.1% market share in 2025,
supported by China's battery manufacturing ecosystem, EV production, and
advanced battery-material supply chains. The regional market was valued at USD
20.30 billion in 2025 and is expected to exceed USD 50.81 billion by
2035.
North America's market was valued at USD 9.08 billion in
2025 and is projected to reach USD 22.72 billion by 2035, while
Europe's market was valued at USD 8.22 billion and is forecast to exceed
USD 20.58 billion by 2035.
LFP leads battery chemistry
Lithium iron phosphate (LFP) accounted for 38.3% of the
market in 2025, followed by NMC at 34.7%. LFP is supported by lower
costs, strong thermal stability, and long cycle life, and represented more than
90% of global stationary battery-storage installations in 2025.
Electric vehicles dominate applications
Electric vehicles accounted for 55.8% of market revenue
in 2025, making them the leading application. Energy storage systems
held 19.7%, supported by renewable-energy integration, grid modernization,
and increasing stationary battery deployment.
Recycling and advanced anodes create opportunities
Battery recycling is creating opportunities to reduce
dependence on newly mined materials. Recycled-material input rates reached more
than 40% for nickel and cobalt and around 20% for lithium in 2023.
Meanwhile, the development of silicon-rich and silicon-carbon anodes is
creating opportunities across materials, manufacturing equipment, cell design,
and battery management technologies.
Competitive landscape
Key companies include CATL, BYD Company Limited, LG
Energy Solution, Panasonic Energy, Samsung SDI, SK On, CALB Group, Gotion
High-Tech, EVE Energy, Envision AESC, SVOLT Energy Technology, and Sunwoda
Electronic.
Explore the Full Report: https://www.cervicornconsulting.com/next-generation-lithium-ion-battery-marketx